

Victoria-based private equity real estate investment firm Merchant House Capital is facing a second insolvency, The Realist has learned.
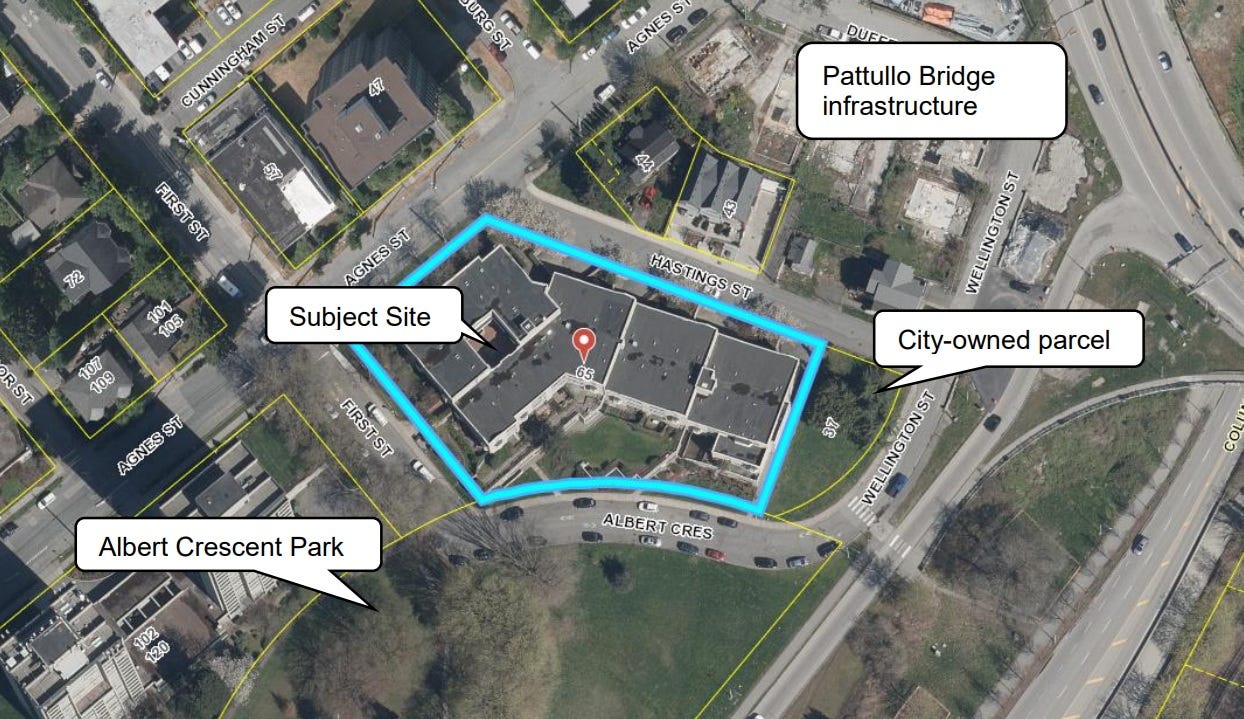
The subject property is 65 First Street in New Westminster, located right next to Albert Crescent Park and steps away from the Fraser River and Pattullo Bridge, which was recently decommissioned and replaced by the stal̕əw̓asəm Bridge.
The site is currently occupied by a low-rise building called Kinnaird Place with 61 strata units and was acquired by Merchant House Capital in 2021 for $22,735,920. The individual strata units are beneficially owned through Kinnaird Konversion Limited Partnership and Kinnaird Konversion GP Inc. under 1274877 B.C. Ltd.
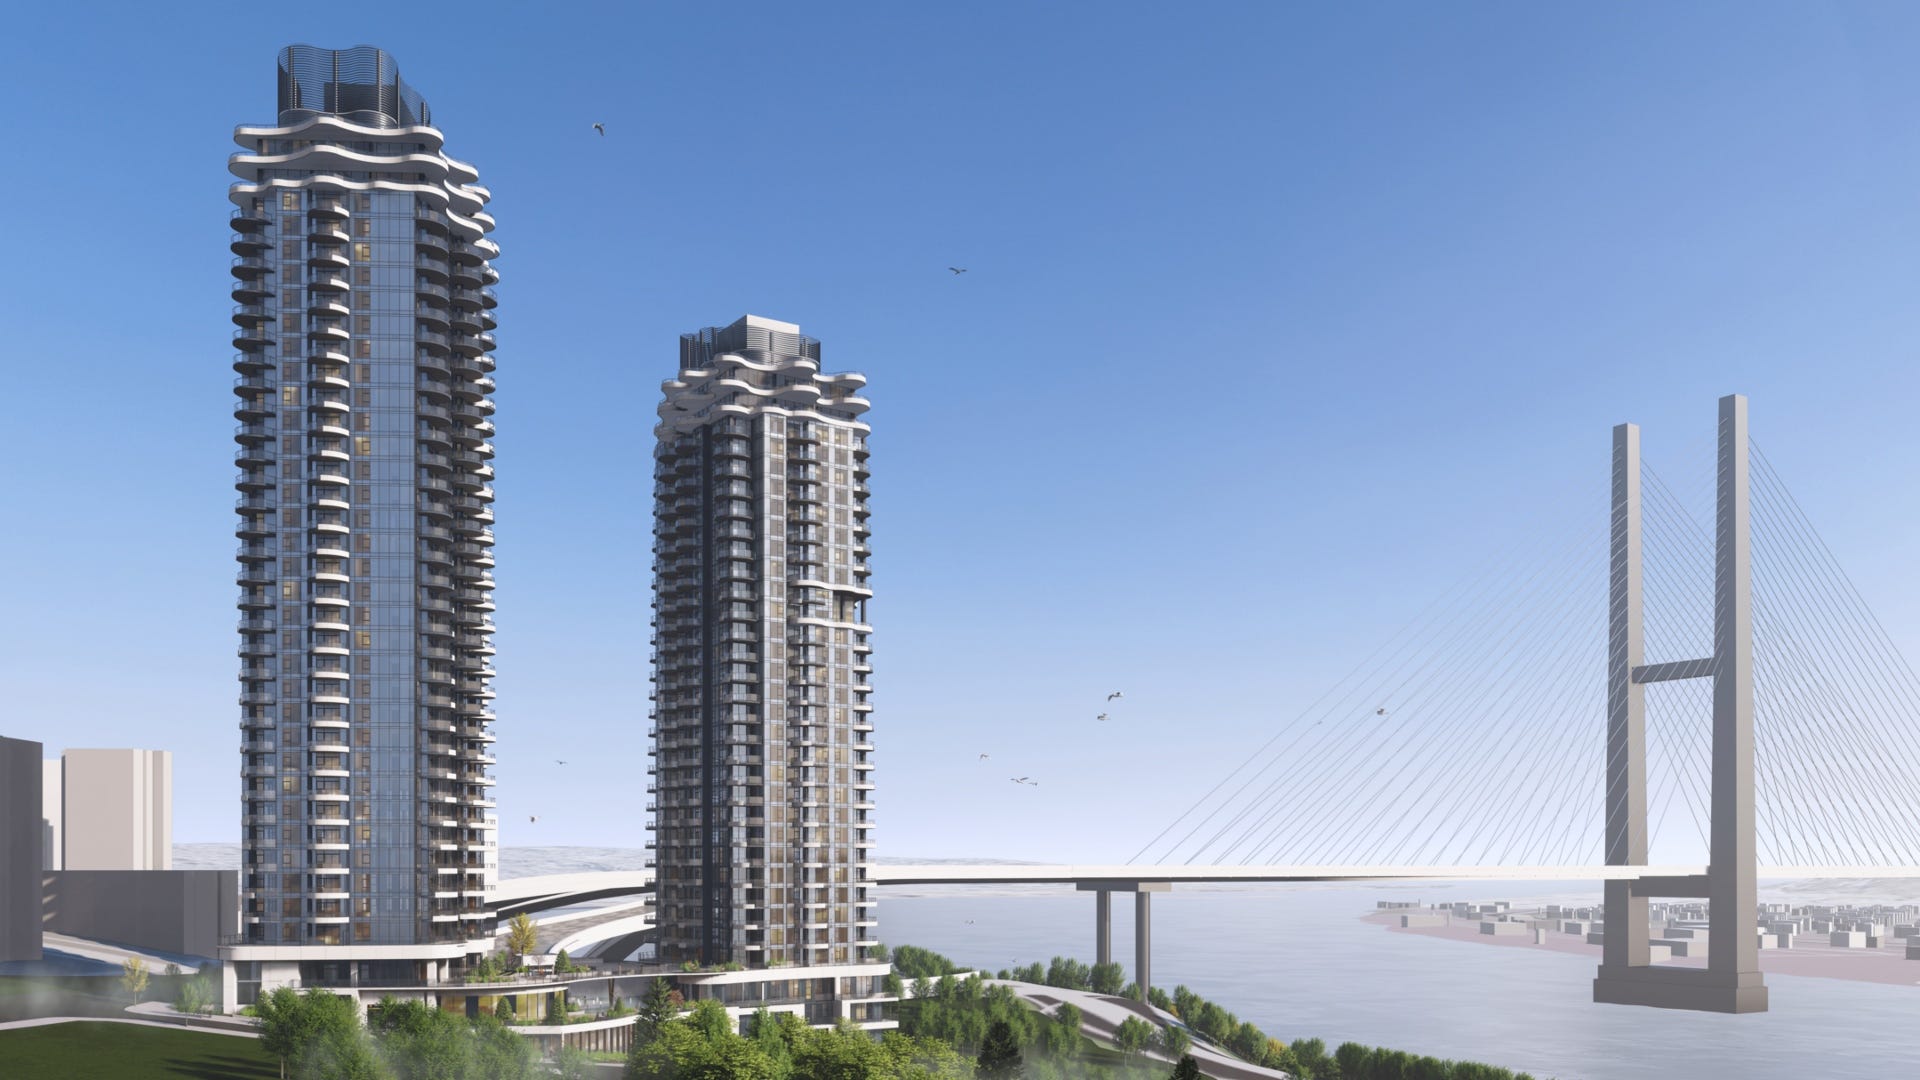
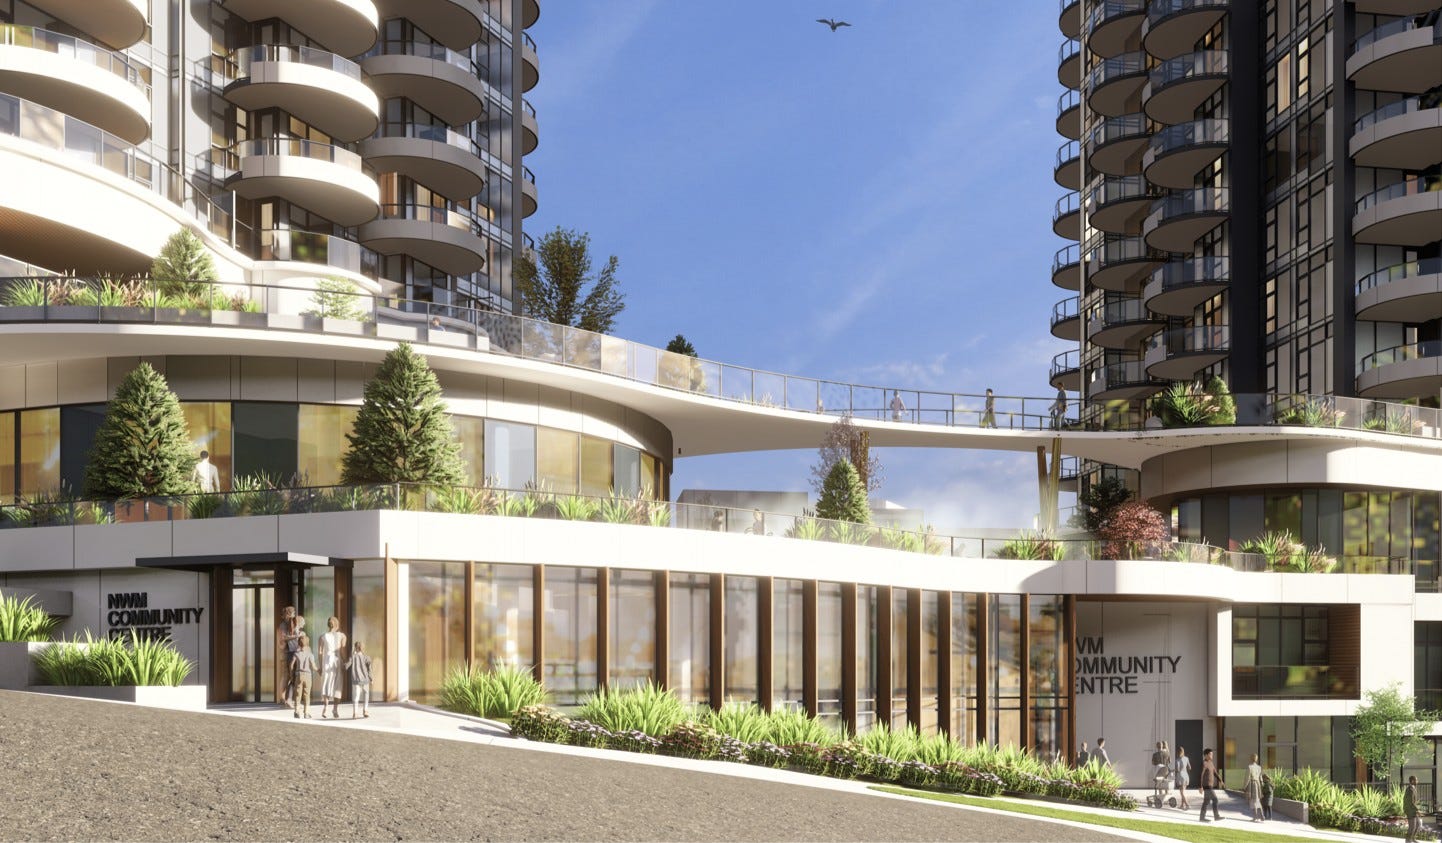
For the site, Merchant House has proposed a 35-storey and 30-storey tower with a total of 304 strata units, 299 market rental units, and 30 below-market rental units, according to a December 2024 planning report.
The site is relatively large, hence why it can accommodate two towers, and the project is also made possible in part by the Province’s introduction of transit-oriented area (TOA) legislation.1 Under provincial legislation, the site is considered a Tier 3 TOA. Council granted first, second, and third readings (conditional approval) for the project on April 9, 2025.
Pursuant to the project, Price Capital Partners Inc. agreed on June 16, 2025, via a promissary note, to provide the borrower with an interim land loan of $5,902,208.22, with interest accruing at 8% per annum. According to their receivership application, Price Capital’s mortgage was second-ranking after a mortgage held by Portage Capital Nominee Corp.
In an affidavit sworn on December 15, 2025, Price Capital President Michael Foy said that Portage Capital notified the borrower on October 10, 2025 that they had missed an interest payment and thus defaulted. On October 17, Price Capital then informed the borrower that default on the Portgage Capital mortgage was considered a default on the Price Capital mortgage as well.
According to Foy, the borrower has failed to make interest payments since October 2025 and has not repayed the loans. The receivership application was granted by the Supreme Court of British Columbia on February 17, as of which $18,663,414.38 was owed to Portage Capital and $6,353,820.29 was owed to Price Capital, with interest continuing to accure.
A Stalking Horse Bid
As I reported for Western Investor in October, the 65 First Street property had already been listed for sale by Avison Young for several months when Merchant House Capital’s Victoria Press Building project on Vancouver Island was placed under receivership last August, so this insolvency comes as no surprise.
The listing does not appear to be online anymore, but should be back online soon as the Supreme Court also approved the court-ordered sales process for the property last week, with Avison Young leading the process.
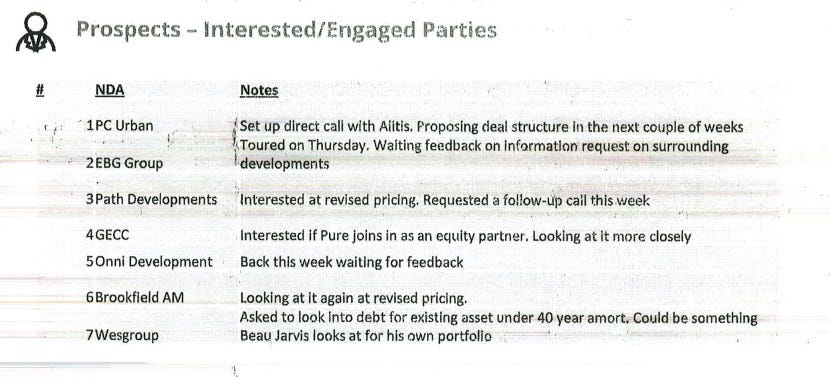
According to a progress report filed by Avison Young in August 2025, they had a list of 68 prospective purchasers, which they whittled down to seven “interested/engaged parties”: PC Urban, EBG Group, Path Developments, Global Education Communities Corp, Onni Group, Brookfield Asset Management2, and Wesgroup.
However, Price Capital has themselves submitted a stalking horse bid — a “floor” bid contigent on no superior offers being found during the sales process — with a purchase price equivalent to the outstanding amounts owed to the two lenders and the court-appointed Receiver.3 According to the Receiver, the sales process will have a final bid deadline of April 3 and proceed to an auction if needed.
The price guidance has not been disclosed, but is usually set at a number higher than the outstanding debt — around $25 million.4 The market will ultimately determine what price can be achieved, but there already exists some doubt, as Foy said an appraisal they received5 valued the property at $21,220,000 as of October 2025, which he notes is at least $3 million short of what is needed for both lenders to fully recover what they’re owed. This affects Price Capital more than Portage Capital because Price is the second-ranking charge holder.
“Due to limited market interest, which Price Capital attributes to current softness in the market, Price Capital has determined that acquiring the Lands is necessary to protect its position as a secured lender in a secondary position behind Portage with a shortfall between the Appraised Value and the combined amount of the Portage Indebtedness and the Price Capital Indebtedness,” said Foy in his affidavit. “Price Capital intends to hold the Lands and pursue a sale when market conditions improve.”
As I’ve reported for Western Investor, lenders are increasingly being forced to submit credit bids like this because of the soft market.
Foy also notes in his affidavit that they intend to complete the transaction via a reverse vesting order — a share sale — in order to avoid the property transfer tax, which would be around $600,000 based on the appraised value. We’ll see what happens with the sales process.
I mentioned this project in a previous article for Storeys about transit-oriented development in New Westminster.
You might be surprised to see Brookfield, but it’s not that surprising because they are developing a project nearby at 810-824 Agnes Street.
No exact amount has been outlined because the debt and fee amounts will continue to change during the sales process.
When it was listed last year, the asking price was $28 million.
By D.R. Coell & Associates.